
At a glance
Sheng Siong Group Ltd management and its retail network operations
Delivered top-line expansion with S$1.3 billion revenue and solid bottom-line net profit growth of S$125.5 million
During the first nine months of financial year 2026 ending 30 September 2026
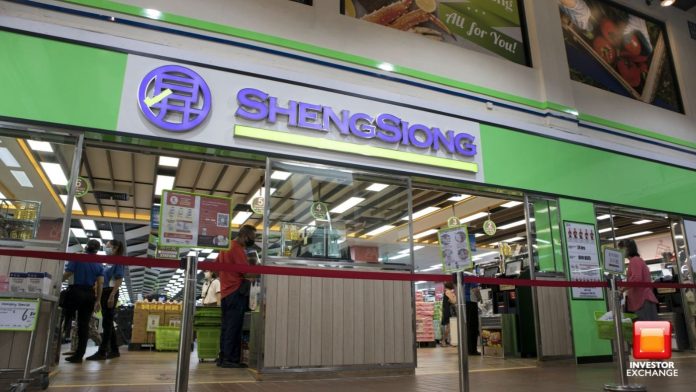
Across 92 Singapore heartland stores, six China branches, and the Singapore Exchange corporate retail sector
Disciplined store expansions and higher-margin product sales countered sticky inflation, rising staff costs, and declining interest income
By opening seven new branches and increasing higher-margin housebrand and fresh produce sales to expand gross margins
Sheng Siong Group Demonstrates Resilience and Expansion
Sheng Siong Group Ltd has released its business updates for 3Q FY2026 and 9M FY2026, demonstrating remarkable operational durability across Singapore’s heartland supermarket sector. In an economic landscape marked by sticky core inflation, statutory wage escalations, and aggressive retail promotion, the household brand delivered top-line expansion and solid bottom-line growth. Total revenue for 9M FY2026 reached S$1.3 billion (+9.9% YoY), while net profit rose to S$125.5 million (+8.1% YoY). By combining disciplined store network expansion with high-margin product mix enhancements and a pristine zero-debt balance sheet, Sheng Siong continues to protect operating profitability while scaling its footprint.
Gross Margin Expansion Defies Inflationary Pressures
Despite ongoing food inflation and rising operational input costs, Sheng Siong successfully expanded its gross profit margins across both the quarterly and nine-month trailing periods. Gross profit margin for 3Q FY2026 expanded by 0.7 percentage points to 32.2% (up from 31.5% in 3Q FY2025), while the 9M FY2026 gross profit margin widened by 0.9 percentage points to 32.0% (up from 31.1% in 9M FY2025).
This structural margin enhancement reflects management’s continuous focus on optimizing its product sales mix. By actively steering consumer purchasing toward higher-margin fresh produce categories and broadening the selection of its proprietary house brand goods, the company has successfully increased profitability per transaction basket. This expansion underscores Sheng Siong’s robust domestic pricing power and supply chain efficiency, confirming its capacity to pass through raw input cost increases while preserving its value proposition for core heartland shoppers.
“We pride ourselves on our service and quality, adding a personal touch to the way we deliver value to our stakeholders.”
Rapid Store Expansion Outpaces National Retail Trends
Physical outlet expansion remains Sheng Siong’s main engine for revenue acceleration. During 9M FY2026, the group opened 7 new stores in Singapore, including 3 strategically launched in 3Q FY2026 at Hougang Street 13, Rivervale Crescent, and Woodlands Avenue 5. This brought its domestic footprint to 92 locations and total group store count to 98 (including 6 in China).
Total Singapore retail floor space expanded to 799,775 sq. ft. as of 30 September 2026 (up from 723,648 sq. ft. a year earlier), easily offsetting the strategic closure of 2 outlets at Elias Mall and Thomson Imperial Court. From an operational efficiency perspective, revenue density remained firm: Singapore operations achieved a revenue per square foot of S$1,645 in 9M FY2026 compared to S$1,667 in 9M FY2025, demonstrating consistent sales productivity even as total retail area grew by double digits.
Sheng Siong’s top-line delivery continues to decouple favorably from broader industry benchmarks. Singapore’s national Supermarkets & Hypermarkets sales index contracted 2.6% YoY in July 2026 before registering a modest 1.6% uptick in August. In comparison, Sheng Siong delivered a 6.2% YoY revenue increase in 3Q FY2026 to S$441.5 million. This baseline comparison is particularly impressive given that 3Q FY2025 revenues were bolstered by widespread SG60 voucher disbursements.
| Metric | 3Q FY2026 (S$m) | 3Q FY2025 (S$m) | YoY Change (%) | 9M FY2026 (S$m) | 9M FY2025 (S$m) | YoY Change (%) |
| Revenue | 441.5 | 415.5 | +6.2% | 1,296.8 | 1,180.2 | +9.9% |
| Gross Profit | 142.3 | 131.1 | +8.6% | 414.7 | 366.6 | +13.1% |
| Net Profit | 44.6 | 43.8 | +1.8% | 125.5 | 116.1 | +8.1% |
| Gross Margin (%) | 32.2% | 31.5% | +0.7 ppts | 32.0% | 31.1% | +0.9 ppts |
Wage Hikes and Digital Fees Squeeze Net Profit Margins
While gross margins expanded, net profit growth experienced notable moderation in 3Q FY2026 (+1.8% YoY to S$44.6 million) relative to 9M FY2026 (+8.1% YoY to S$125.5 million). Consequently, net profit margin for 3Q FY2026 compressed by 0.4 percentage points YoY to 10.1% (down from 10.5% in 3Q FY2025), while 9M FY2026 net margin adjusted slightly by 0.1 percentage points YoY to 9.7% (down from 9.8% in 9M FY2025). This margin squeeze stems from compounding overhead pressures across labor, payment processing, and quick-commerce platform infrastructure:
- Selling & Distribution Expenses: Jumped 14.2% YoY in 9M FY2026 to S$226.9 million. Operational staff costs grew by S$21.8 million YoY, driven by new store headcount additions, higher performance-linked variable bonuses, and mandatory salary increases under the Progressive Wage Model (PWM) for retail workers implemented in September 2025.
- Administrative Expenses: Grew 13.3% YoY in 9M FY2026 to S$51.4 million. Administrative staff overhead rose alongside digital transaction costs—specifically credit/debit card merchant fees—and platform commissions from its quick-commerce partnership with Foodpanda, which was launched in June 2026.
- Net Finance Income Decline: Net finance income plummeted 92.8% YoY in 9M FY2026 to S$0.2 million (down from S$3.5 million), impacted by lower prevailing interest rates on fixed deposit reserves.
Strategic Capital Deployment and Balance Sheet Strength
Sheng Siong’s fortress balance sheet remains a standout defensive strength, backed by S$388.9 million in cash and cash equivalents as of 30 September 2026 and zero bank borrowings.
Operating cash flow for 9M FY2026 stood at S$120.8 million (compared to S$175.4 million in 9M FY2025). This movement was primarily driven by earlier settlements of trade payables to supply chain vendors, which reduced total trade and other payables by S$56.4 million.
Capital expenditure (PPE payments) rose to S$19.5 million in 9M FY2026 (up from S$13.0 million in 9M FY2025). The capital outflow was principally tied to progress payments for the Sungei Kadut property. Once operational, this major distribution hub is designed to enhance centralized logistics and support a long-term network capacity of at least 120 supermarket branches.
Financing cash outflows reached S$152.8 million, driven by S$113.5 million returned to equity holders in dividend distributions alongside S$35.0 million dedicated to principal lease liabilities.
China Operations Reach Break Even Amid Global Risks
Overseas operations in China (encompassing 6 store locations) accounted for 2.0% of total group revenue in 9M FY2026. Despite sharp price competition in the mainland Chinese retail market, the division successfully achieved operational break-even status for the period.
Looking ahead, management outlined a series of cost and operational headwinds requiring disciplined risk management:
- Cross-Border Spending Leakage: The planned launch of the Johor Bahru–Singapore RTS Link in February 2027 may incentivize cross-border grocery shopping for non-perishable consumer items.
- Cost Inflation Pressures: Diesel and energy price fluctuations, upcoming utility contract renewals at higher prevailing rates, and proposed National Wage Council 2026–2027 guidelines (recommending 6–8% wage increases for lower-income staff) present ongoing operating cost pressures.
What Investors Should Watch Next
Sheng Siong’s investment thesis rests on balancing rapid store network growth with strict cost control and automated supply chain infrastructure.
Upside Catalysts
- Pipeline Tenders: Potential awards from 4 pending public HDB store tenders to expand neighbourhood reach.
- Commercial Leases: Execution of new private commercial leases and the pending lease renewal for the Serangoon North Avenue 5 branch with JTC.
- Fiscal Support: Ongoing CDC voucher programs providing steady tailwinds for heartland grocery spend.
- Productivity Gains: Operational leverage from ongoing investments in automated logistics facilities and AI technology implementations.
Downside Risks
- Labor Expense Inflation: Margin compression stemming from PWM wage ladders and National Wage Council recommendations.
- Promotional Pressure: Potential gross margin erosion from heightened price discounting across rival supermarket chains.
- RTS Link Disruption: Potential leakage in grocery spending following the completion of the cross-border transit connection in early 2027.
Related stories: Japan Foods Holding Rebounds To Profitability In HY2027